

September brought a more restrained flow of new activity to the Lowcountry. Across the broader Hilton Head-area market, fewer homes entered the market, pending sales declined and available inventory was lower than a year earlier. Closings, however, remained almost unchanged, and year-to-date activity continued to show modest gains.
The Beaufort-Jasper market added a different perspective: September closings and sale prices increased year over year, even as new contracts weakened and marketing times lengthened. Together, the reports describe a selective market whose balance depends on geography, property type and price range. The two MLS territories are discussed separately rather than combined into a single Lowcountry total.
New Contracts Softened, While Completed Sales Held More Firmly
The Hilton Head-area market recorded 427 pending sales in September, down 16.3% from September 2025 and 7.0% from August. Closed sales totaled 461, only 0.2% below a year earlier and 1.7% below August. Through September, pending sales remained 2.4% ahead of the first nine months of 2025, while closings were up 0.3%.
The distinction matters. Completed transactions have held more firmly than September contract signings, but the recent reduction in accepted offers deserves attention. Pending sales precede completed transactions; they do not guarantee that future closings will move by the same percentage or on a fixed timetable.
A longer view is also more measured than the monthly decline alone suggests. Hilton Head-area rolling pending sales increased 1.5% over the 12 months ending September, while rolling closings increased 2.1%. Demand has not disappeared, but its most recent monthly pace has softened.
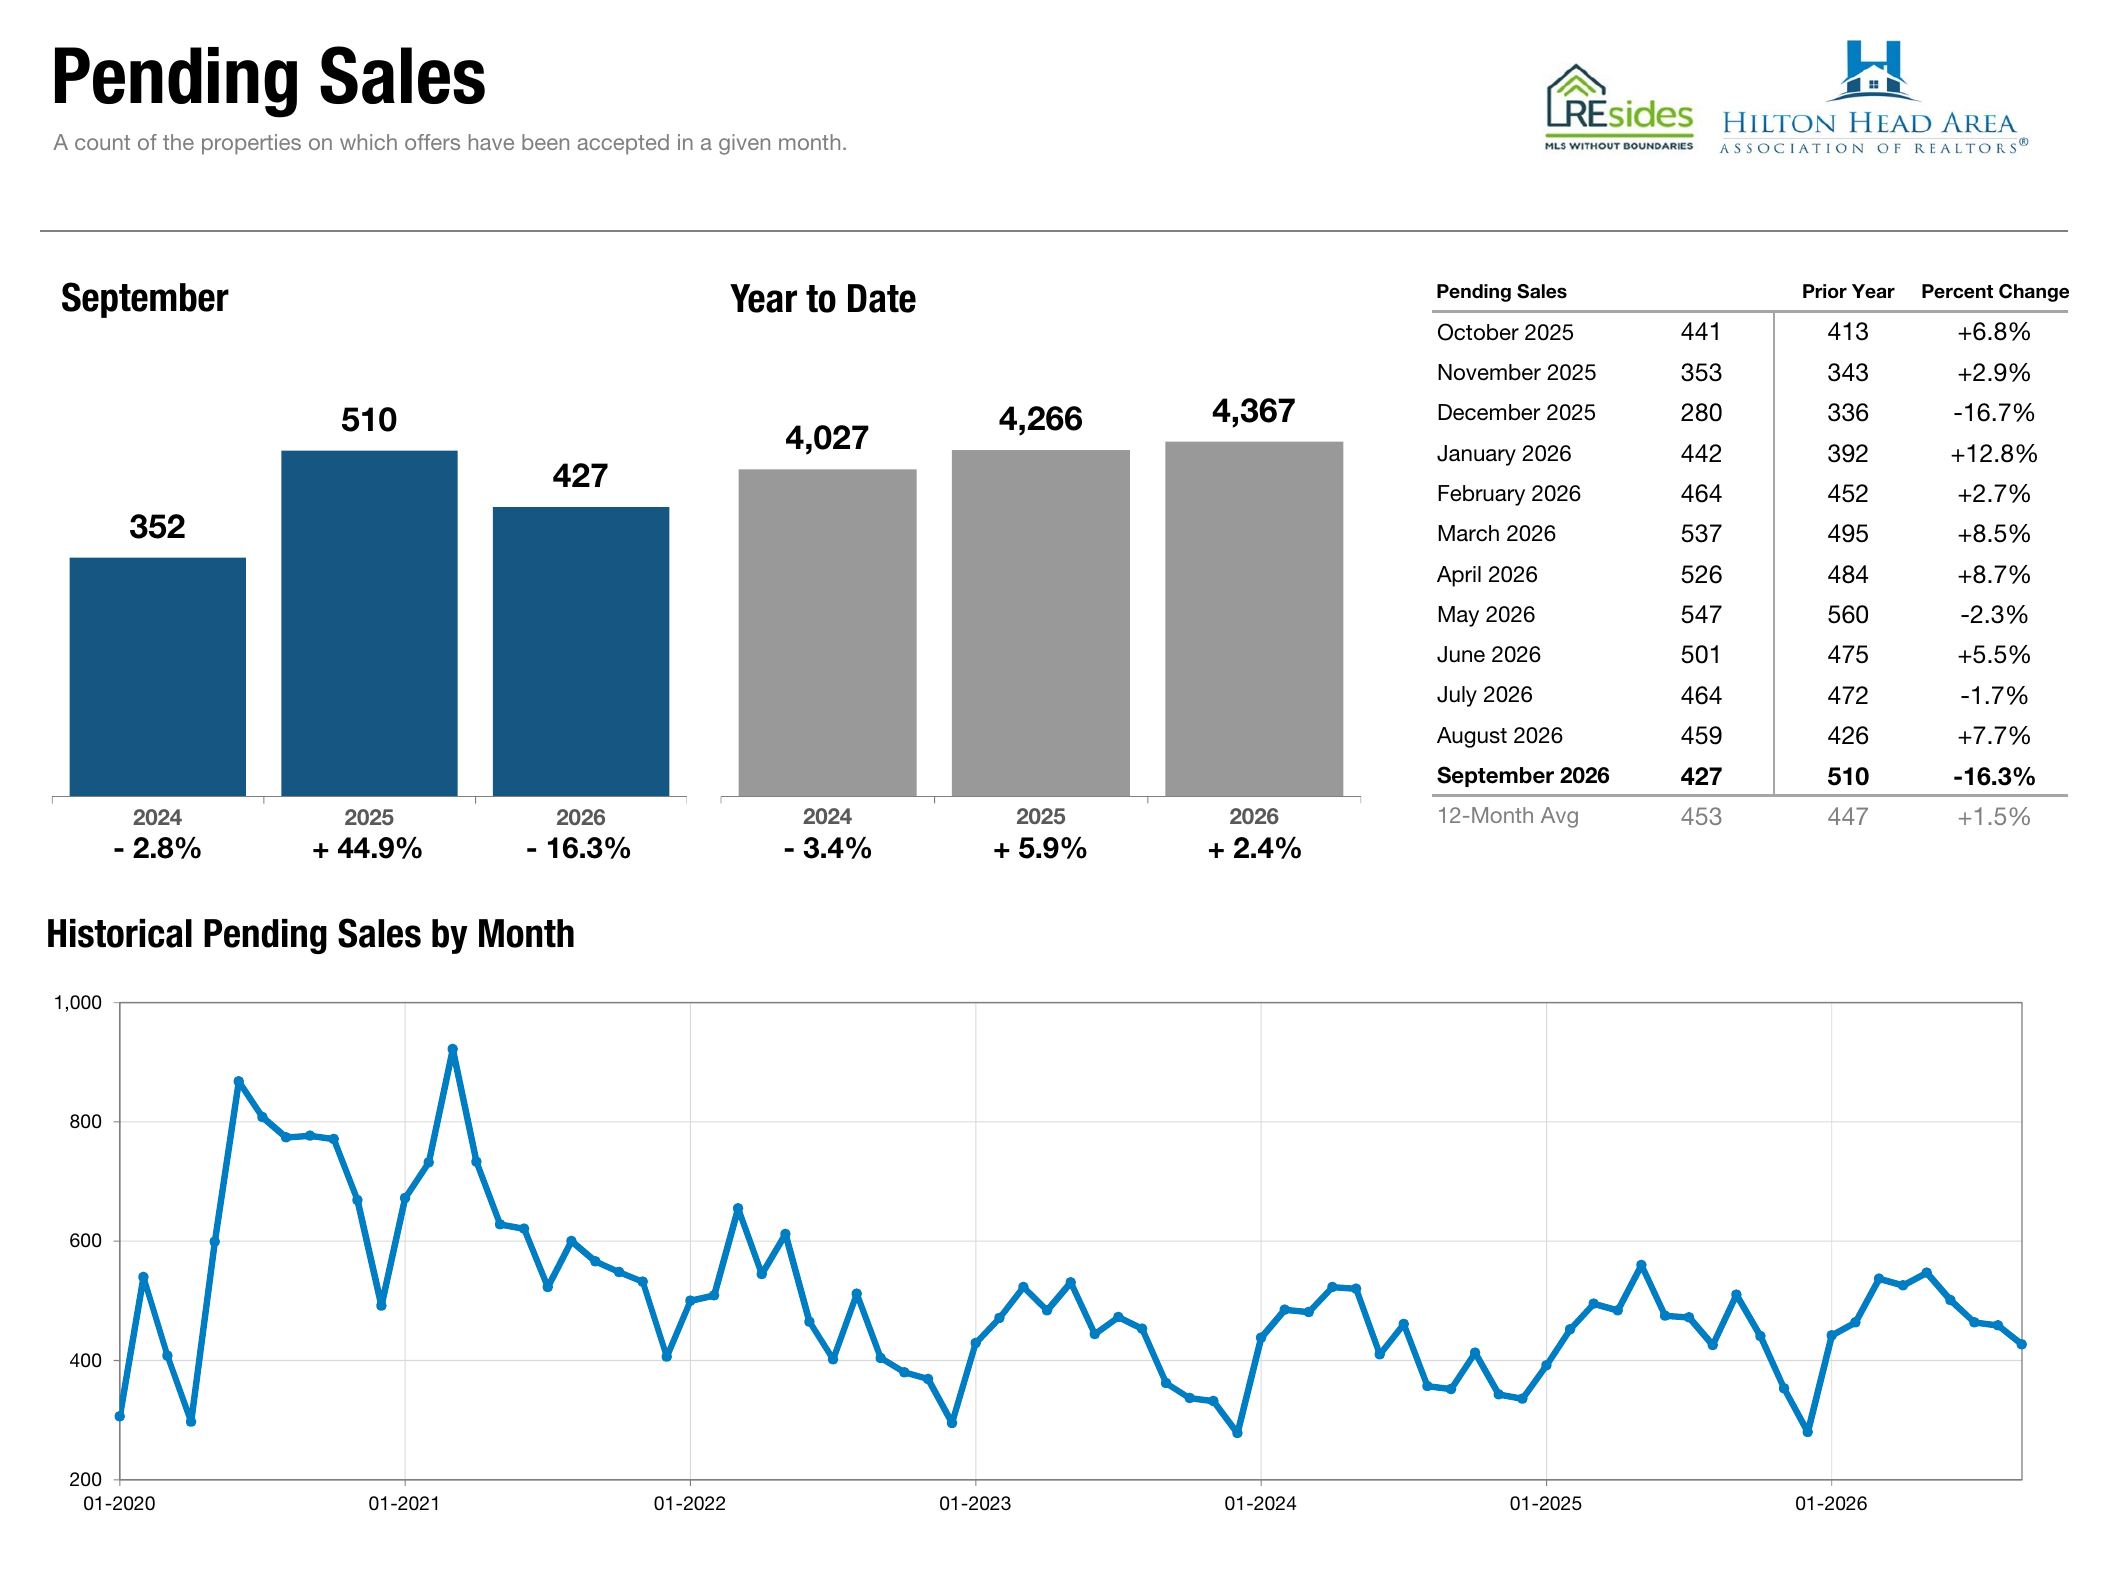
Pending Sales, September 2026, REsides
Fewer Homes Are Entering and Remaining on the Market
New listings in the Hilton Head-area market fell to 441, down 35.7% year over year and 25.1% from August. Inventory ended September at 2,015 homes, down 6.5% from a year earlier and 7.5% from August. Months supply was 4.4, compared with 4.8 last September and 4.7 in August.
That creates a different setting from a market in which rising inventory consistently expands buyer choice. Fewer active homes can reduce direct competition among sellers, but weaker new contracts mean lower supply should not automatically be interpreted as stronger demand.
Property type adds further nuance. Single-family inventory declined 9.2% year over year to 1,355 homes, while condo inventory increased 1.2% to 609. Single-family homes carried 3.9 months of supply, compared with 5.9 months for condos. Buyers and sellers can therefore encounter a different balance depending on the type of property involved.
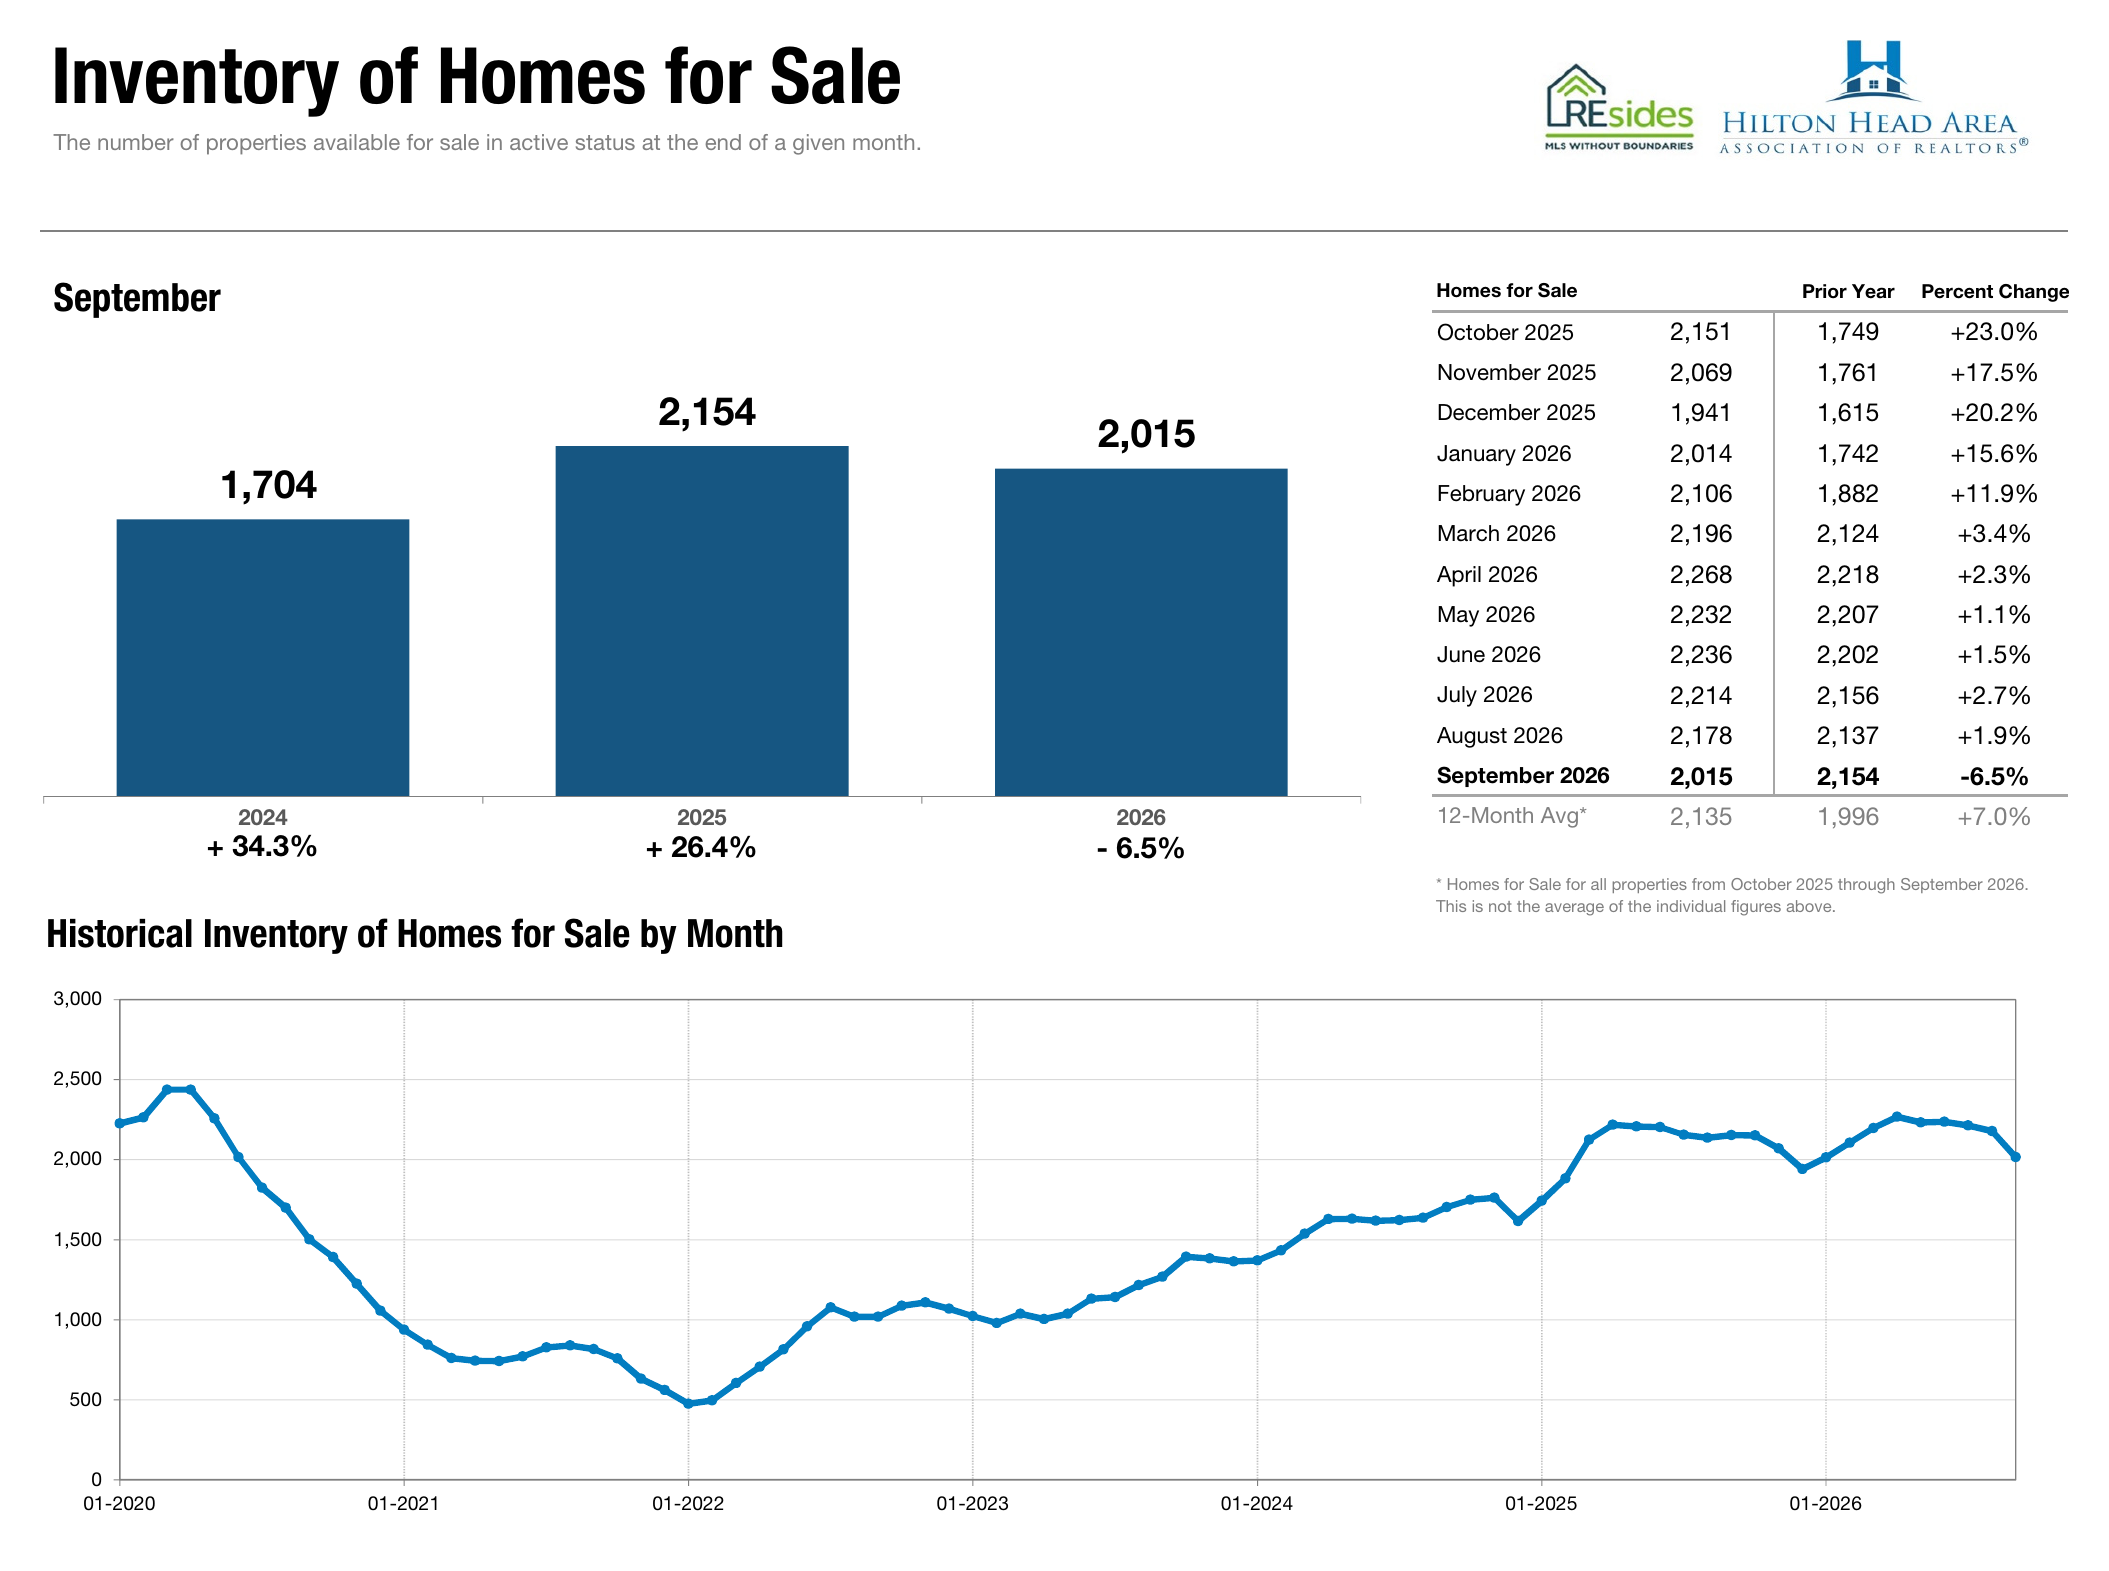
Inventory of Homes for Sale, September 2026, REsides
Marketing Times Improved in September, but the Longer Horizon Remains
Hilton Head-area homes averaged 121 days on market, down 6.9% from 130 days a year earlier and 9.7% from August’s 134 days. This is a meaningful improvement in the monthly pace. It should also be considered alongside the year-to-date average of 131 days, which remained 52.3% above the corresponding 2025 period.
The rolling 12-month average was 131 days, compared with 81 during the preceding period, an increase of 61.7%. The recent improvement therefore does not mean the market has returned to its earlier selling horizon. It indicates a faster September within a market that has generally required considerably more time.
For buyers, time can support a more deliberate evaluation of condition, alternatives and value. For sellers, the lesson is to prepare for the relevant property segment’s pace, rather than assume that lower overall inventory will produce an immediate response.
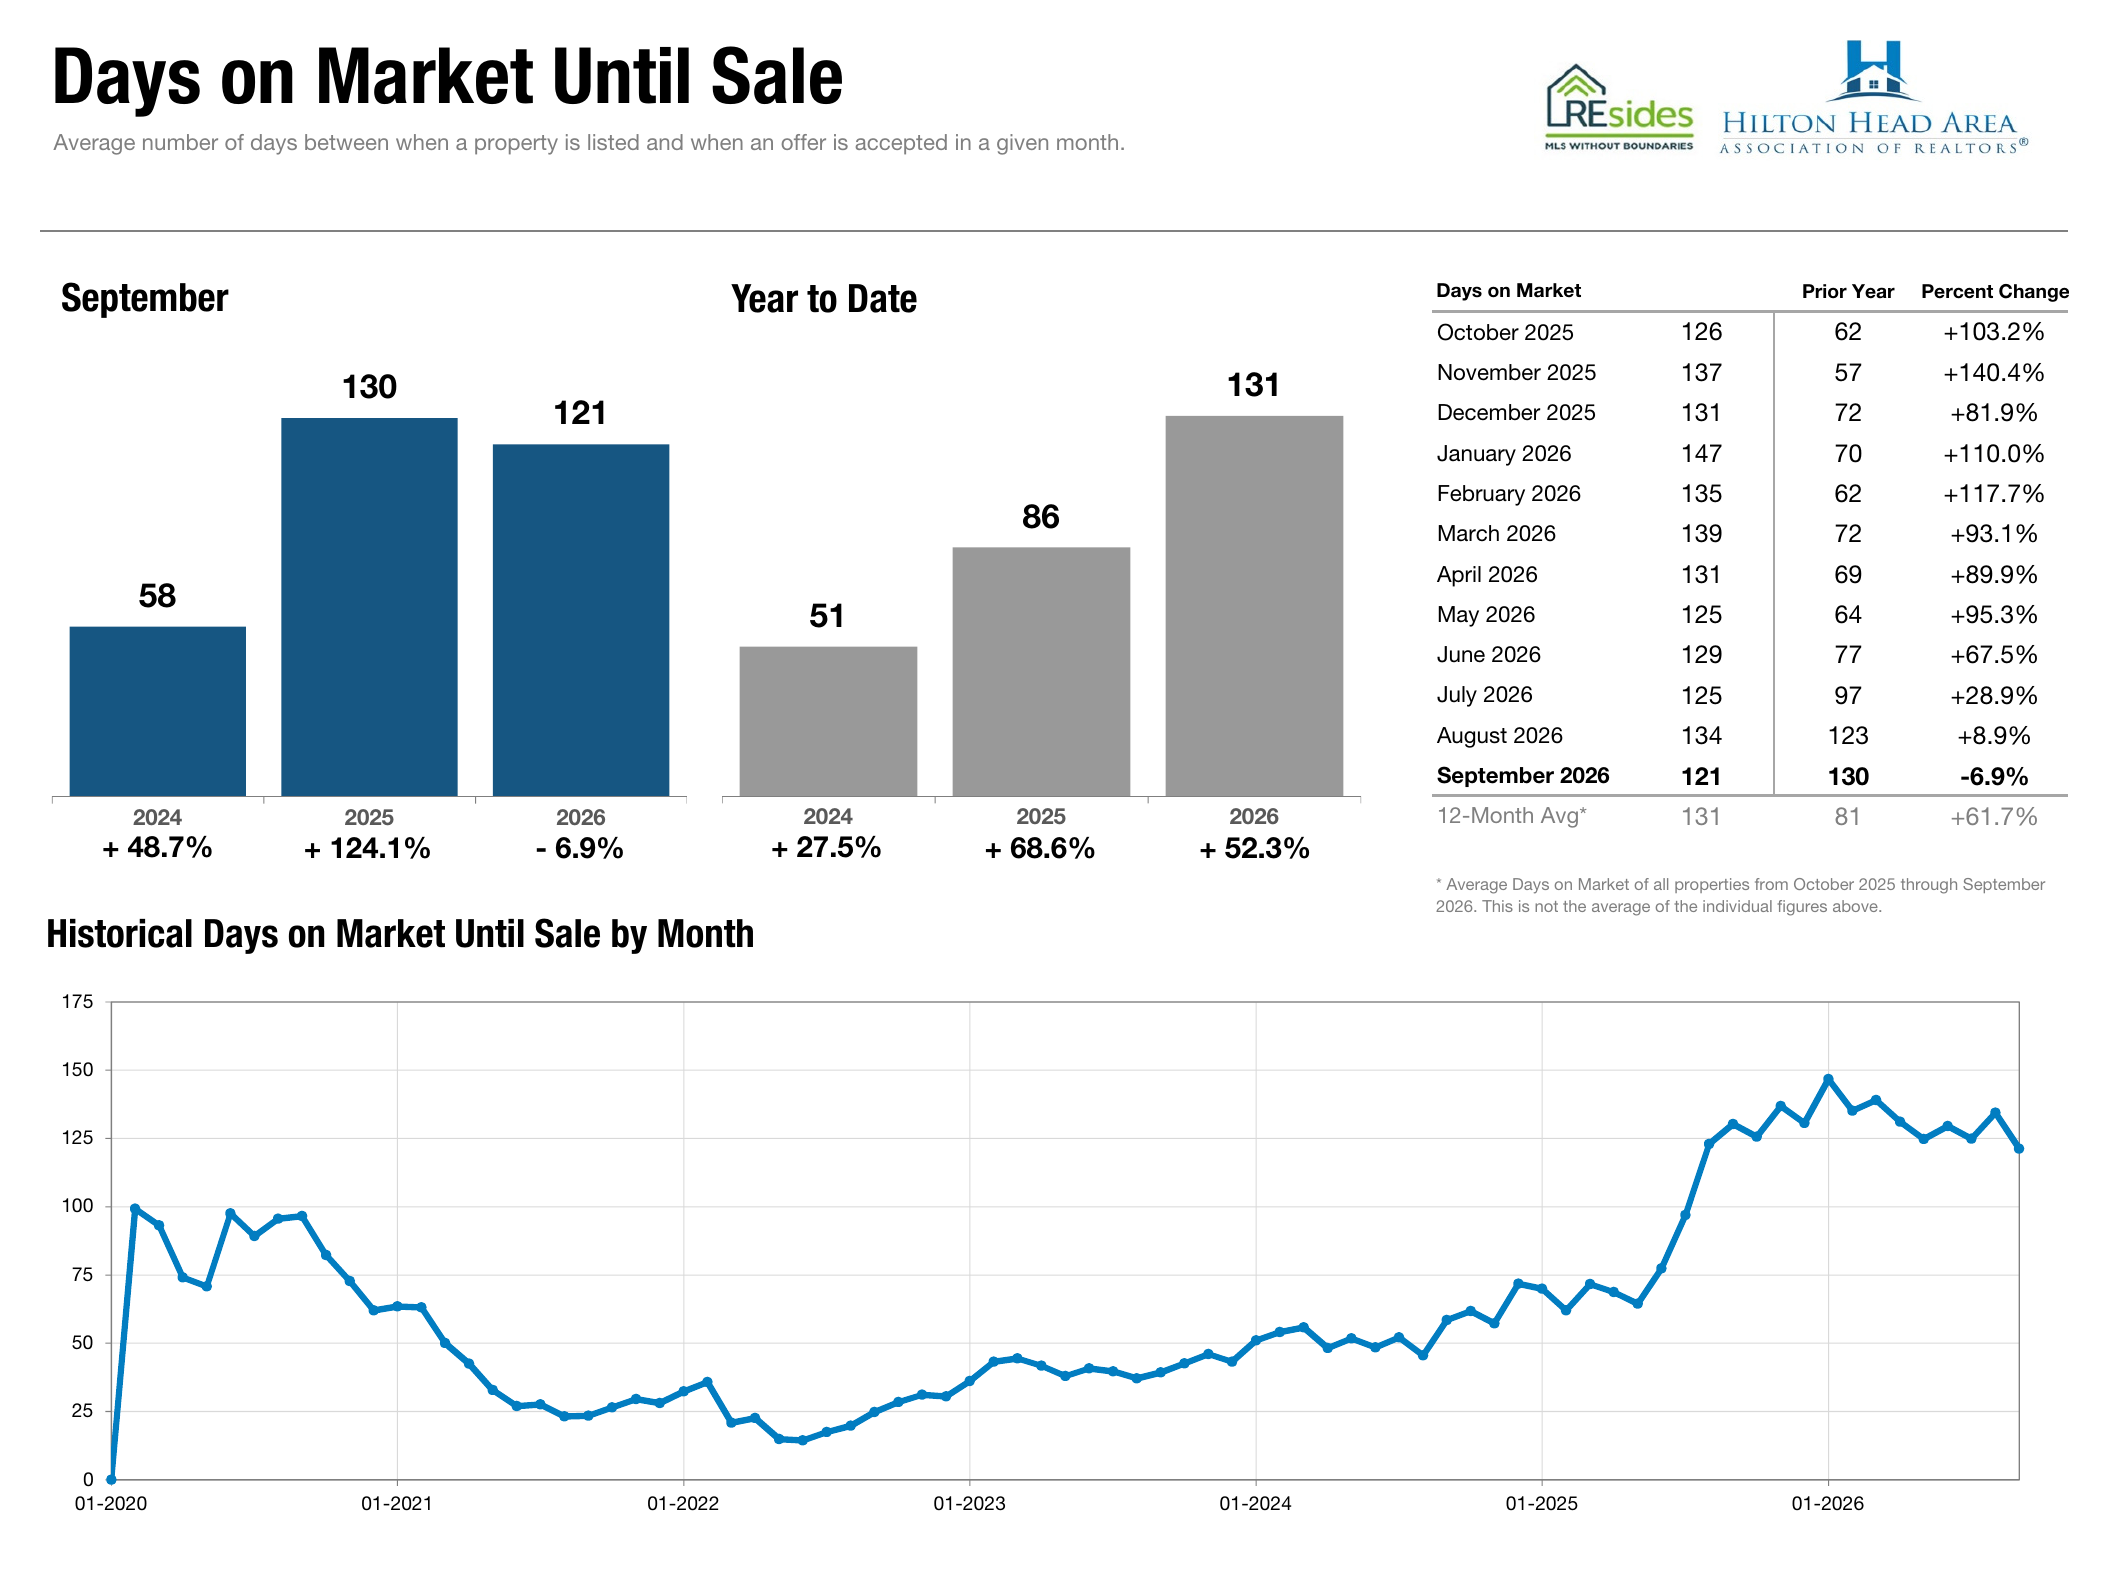
Days on Market Until Sale, September 2026, REsides
Pricing Is Relatively Stable in the Hilton Head-Area Aggregate
September’s median sale price was $535,000, up 1.5% year over year and unchanged from August. The average sale price was $830,580, down 0.7% year over year and 1.4% from August. Through September, the median was essentially unchanged at $550,000, while the average increased 3.6% to $825,144.
These measures answer different questions. The median identifies the midpoint of completed sales; the average is more sensitive to high-value transactions. Neither is a direct measure of appreciation for the same home, and neither should be selected simply because it presents the more favorable result.
The rolling 12-month median declined 0.9% to $545,000. By property type, the single-family median declined 0.2% to $599,000 and the condo median declined 2.2% to $426,000. The evidence supports a measured description of overall pricing, with meaningful differences beneath the regional figures.
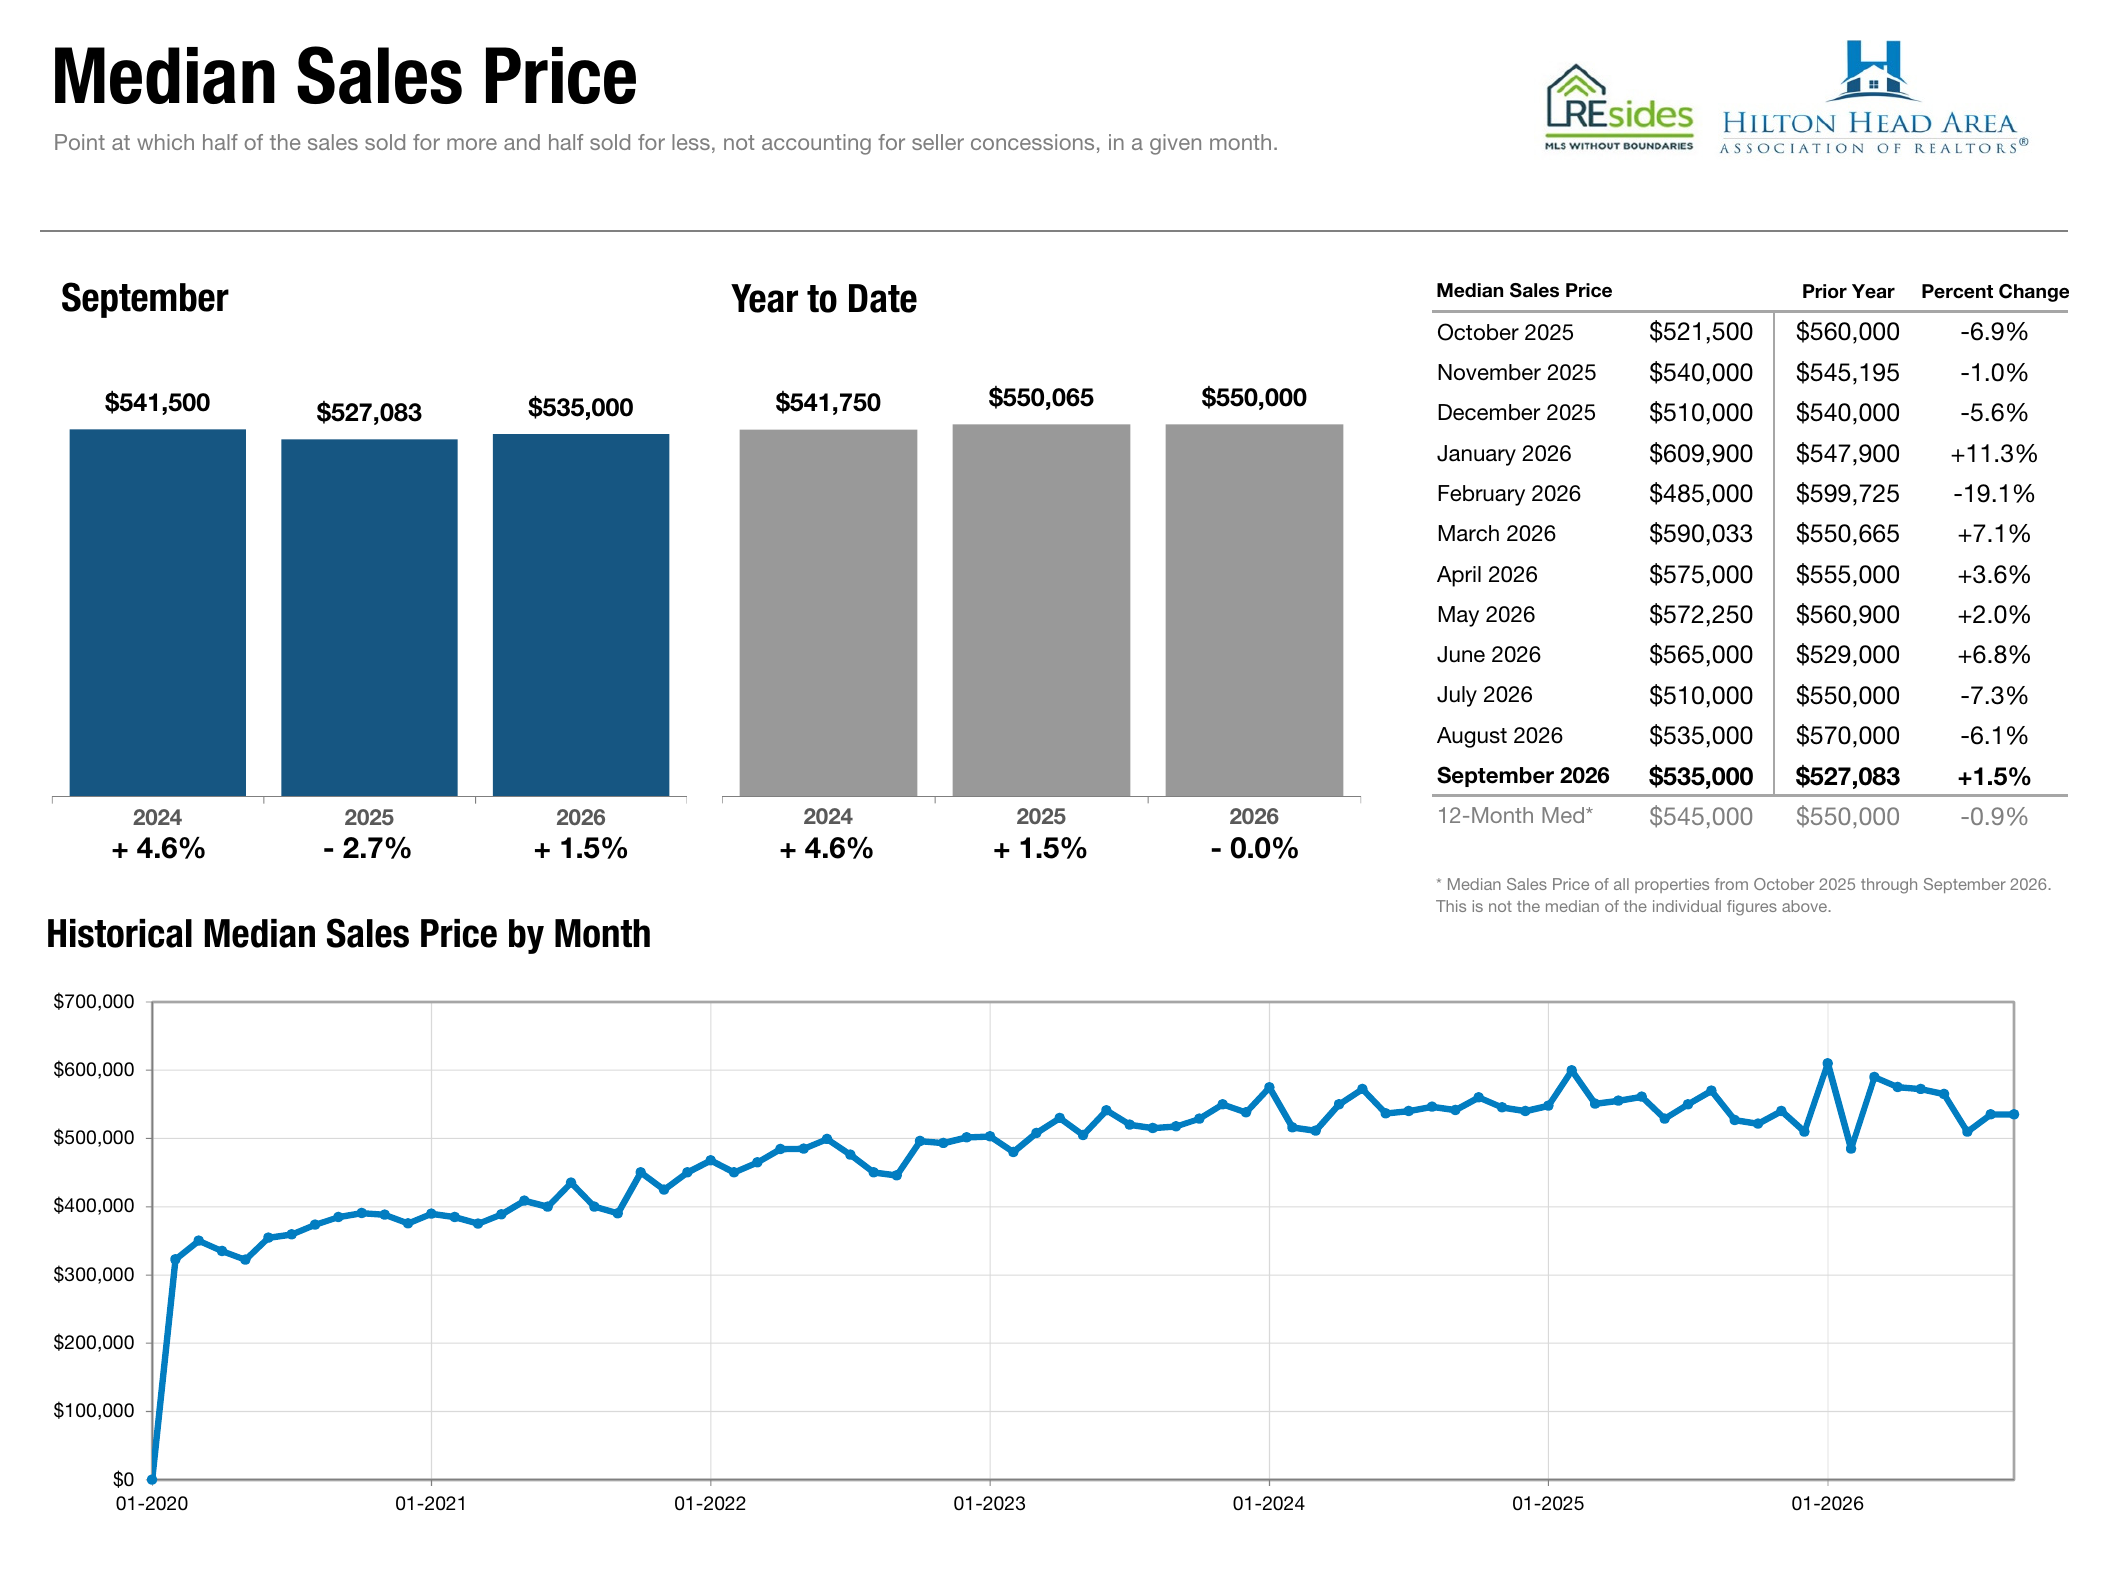
Median Sales Price, September 2026, REsides
Upper Price Ranges Continue to Contribute to Activity
Over the 12 months ending September, Hilton Head-area pending sales above $1 million increased 10.1%, from 1,082 to 1,191. Pending sales at $750,001-$1 million increased 8.6%, while those at $500,001-$750,000 declined 6.6%. The strength is selective, even within the upper portion of the market.
Rolling closings increased 6.9% above $1 million and 8.2% at $750,001-$1 million, compared with a 4.8% decline at $500,001-$750,000. September active inventory above $1 million declined 14.7% to 405 homes, and that bracket carried 4.1 months of supply. At $750,001-$1 million, supply was 3.3 months.
The combination of stronger rolling activity and fewer available homes in these brackets is worth distinguishing from the weaker September contract total. It supports a more specific discussion of upper-tier demand without implying that every high-value property faces the same level of competition.
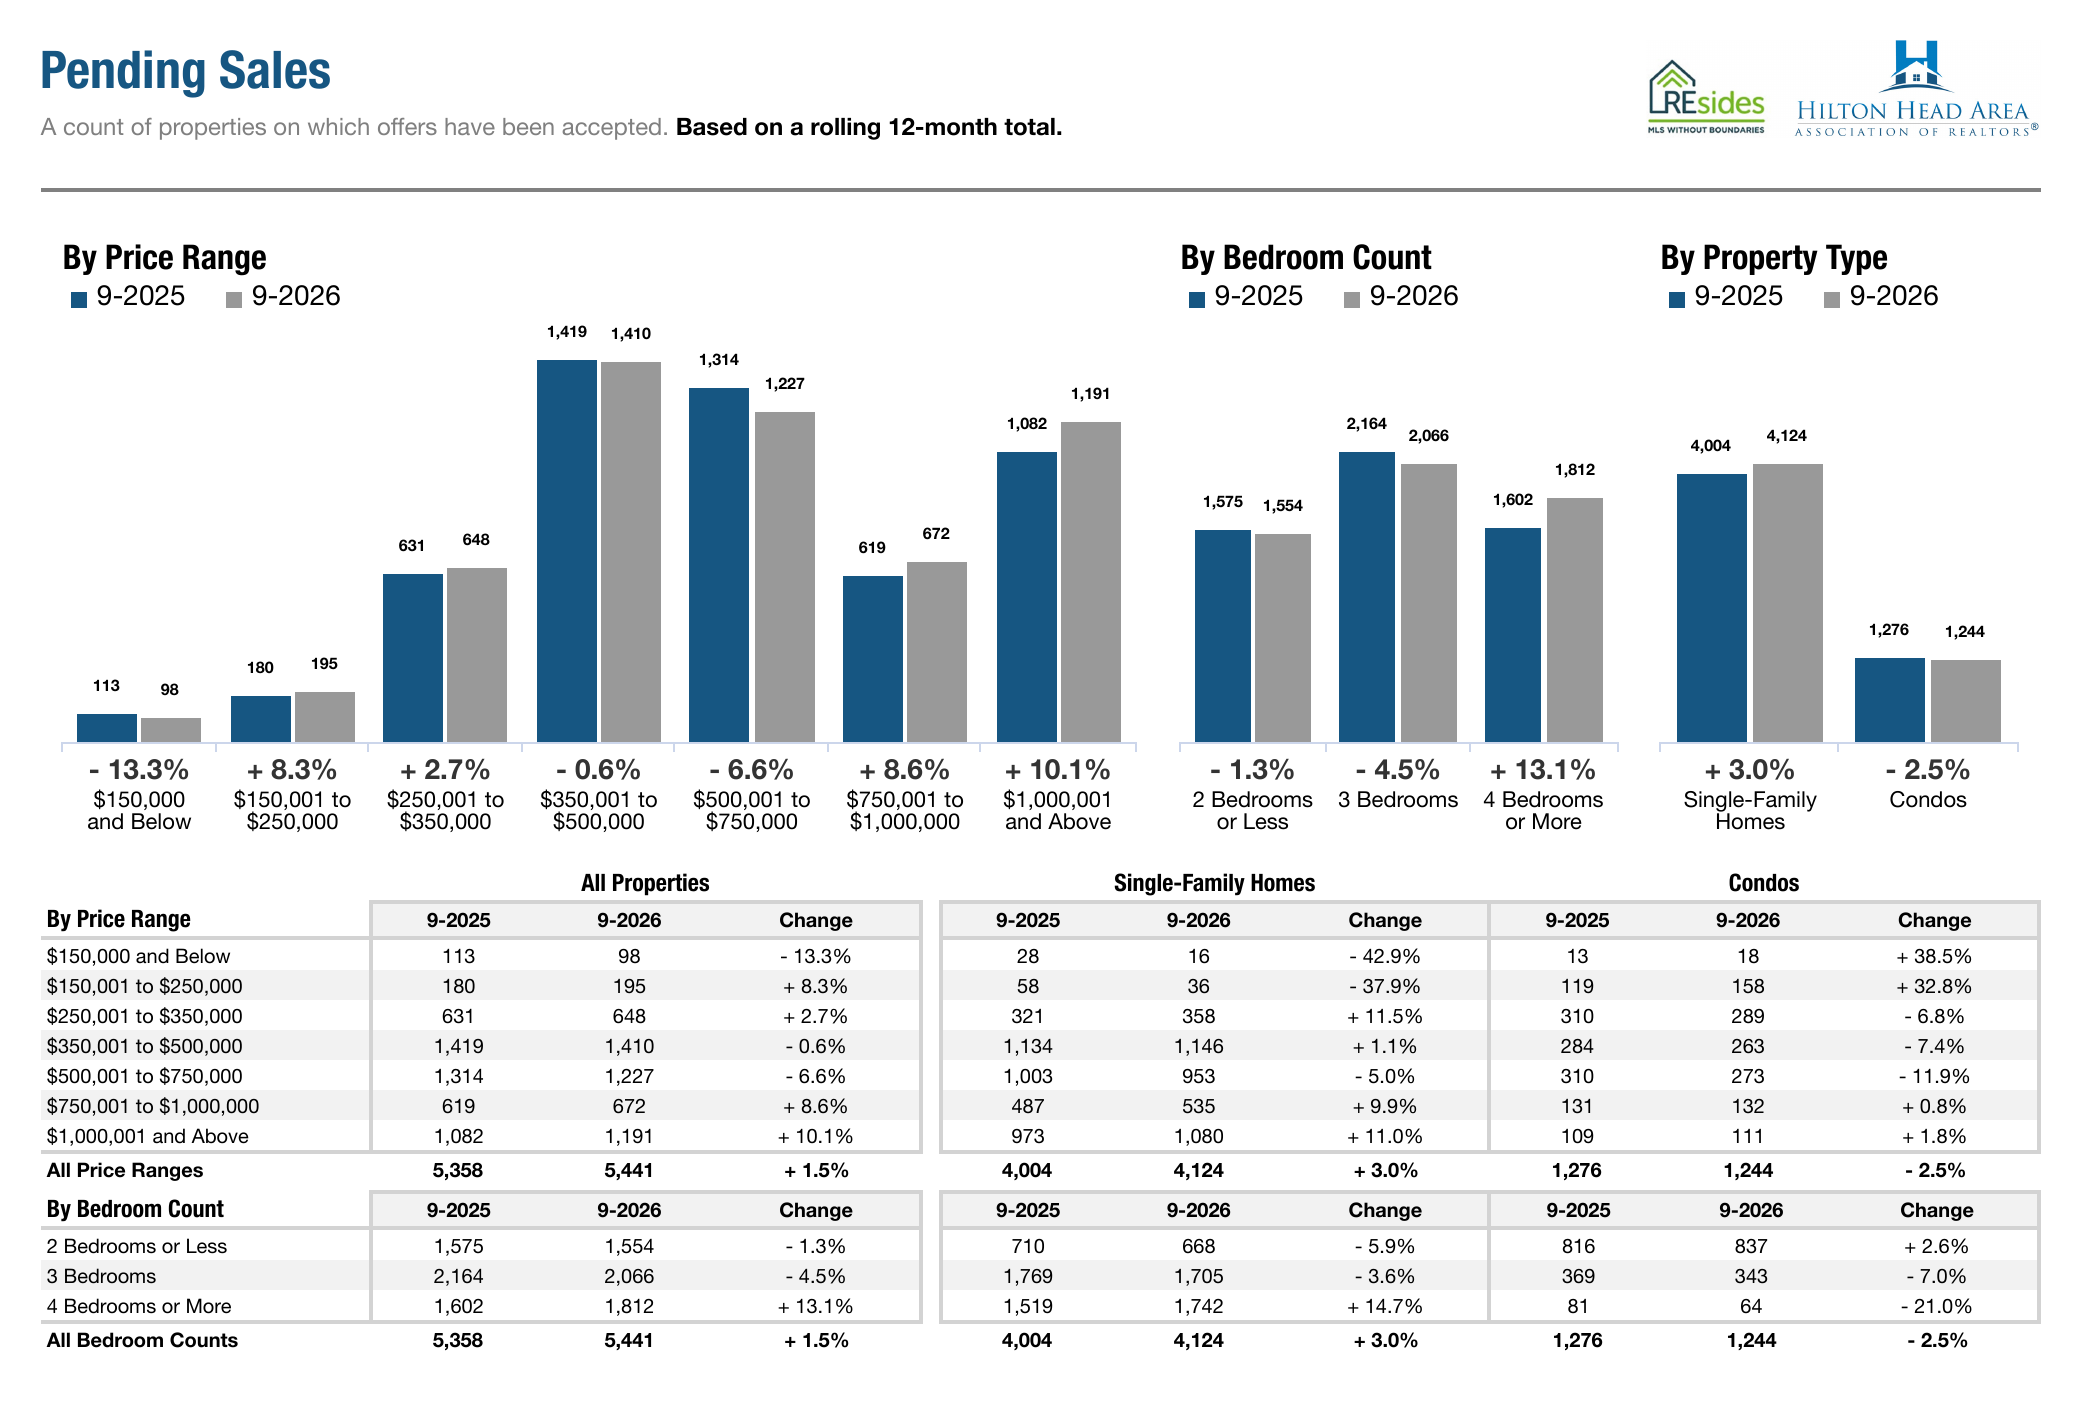
Pending Sales by Price Range, September 2026, REsides
Beaufort-Jasper Shows Firmer Prices, but a Slower Contract Pipeline
The separate Beaufort-Jasper report recorded 251 September closings, up 4.6% year over year but down 9.4% from August. Pending sales fell 19.1% annually to 207 and were 23.3% below August. New listings declined 31.0% year over year to 247. Through September, closings were down 0.3%, while pending sales remained 3.6% ahead of 2025.
Inventory was 1,359 homes, up 1.0% year over year but down 4.6% from August. Homes averaged 136 days on market, up 9.7% annually and 6.3% monthly. The median price reached $465,000, up 11.1% year over year and unchanged from August; the average reached $615,215, up 5.9% annually but down 2.8% monthly.
The longer-term median was less elevated than September’s annual gain: the rolling median increased 0.9% to $440,107. Above $1 million, rolling pending sales increased 22.7% and closings increased 21.4%, while September inventory rose 17.6% and supply stood at 7.0 months. Higher transaction activity and more available choice can coexist.
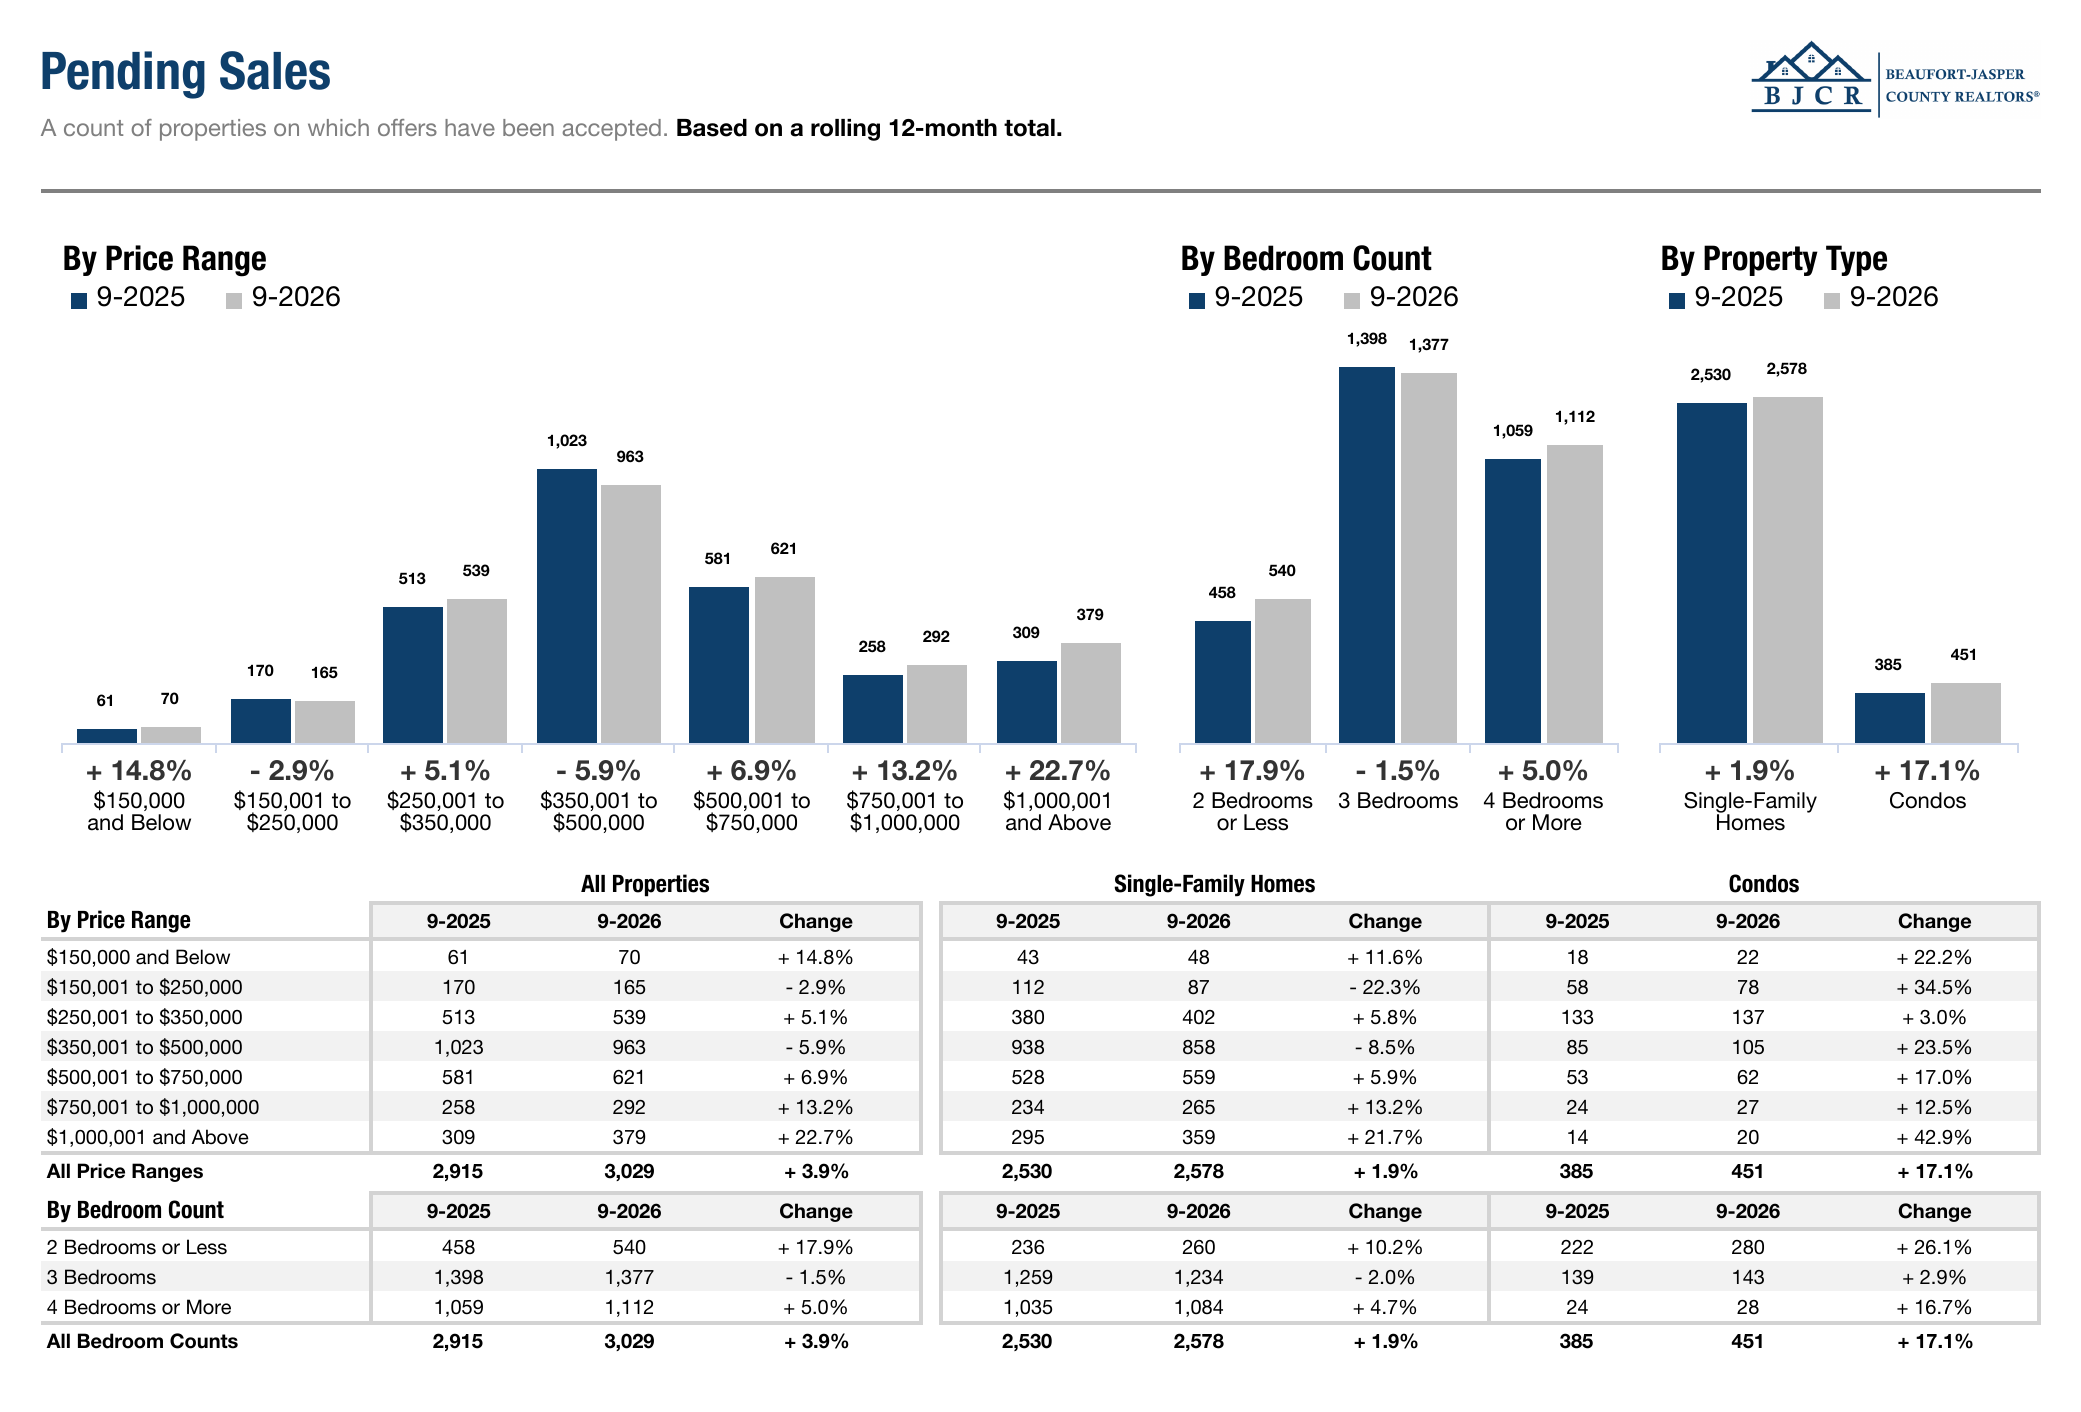
Pending Sales by Price Range, September 2026, Beaufort-Jasper
Hilton Head, Bluffton and Northern Beaufort County Remain Distinct
The Hilton Head Totals local reports show different conditions for detached homes and condos or villas. Detached September closings declined 6.8% to 69, with inventory down 19.6% to 221 and a median price of $1.3 million, up 0.2%. Condos and villas recorded 66 closings, down 12.0%, while inventory edged up 0.5% to 422 and the median increased 18.3% to $532,500. These are property-type medians and have not been combined.
Bluffton’s local report, covering ZIP codes 29910 and 29909, recorded 188 closings, down 6.0% year over year, but year-to-date closings remained up 5.7%. Inventory declined 19.6% to 679, and the September median declined 3.0% to $519,145. Northern Beaufort County recorded 29 closings, up 31.8%, with a median of $450,000, up 14.8%, and inventory down 2.6% to 186. The smaller Northern Beaufort monthly count warrants care when interpreting percentage changes.
Palmetto Bluff adds a further illustration of how a small monthly sample can affect price comparisons. Its nine September closings were down from ten a year earlier, while the median increased 58.0% to $2,725,000. Year-to-date closings were up 71.2% to 101. The report supports discussing increased year-to-date activity, but a large one-month median increase does not establish an equivalent rise in individual property values.
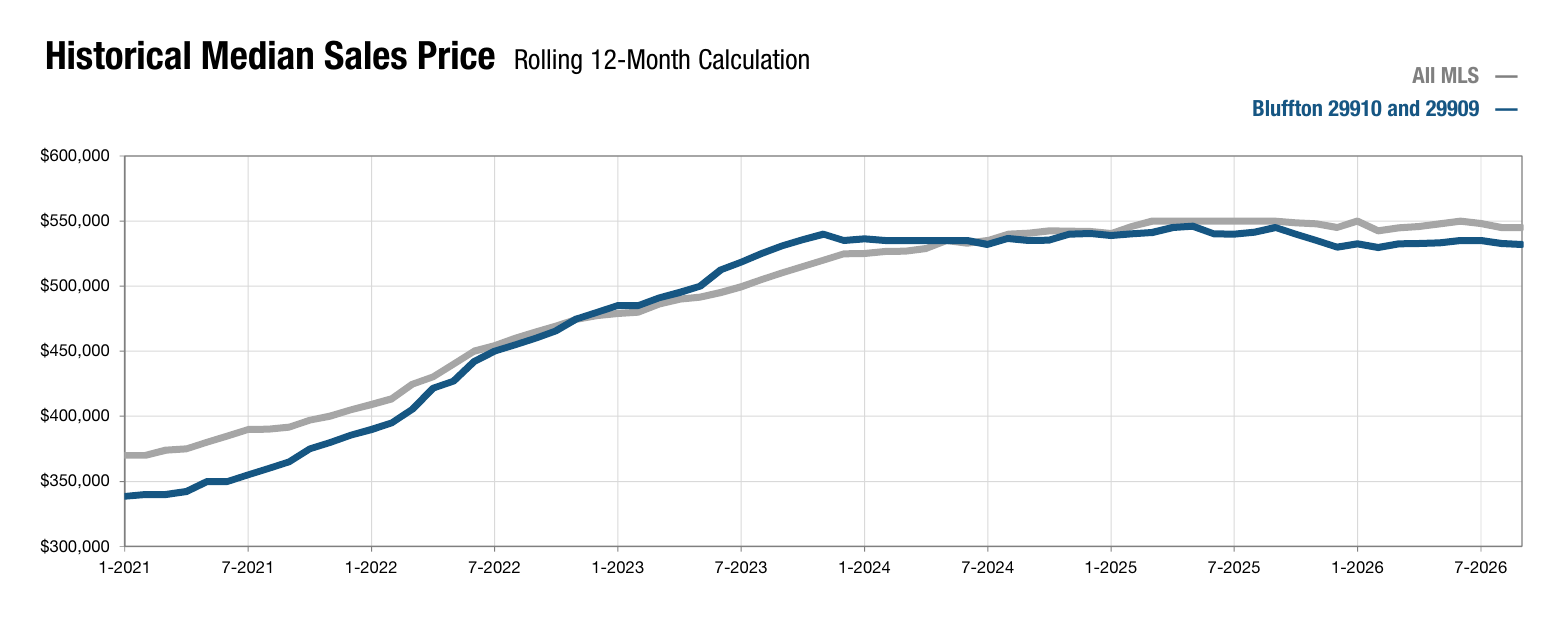
Bluffton Historical Median Sales Price, September 2026, REsides
What This Means for Buyers and Sellers
For buyers, September offers more time for consideration in many segments, but fewer active homes in the broader Hilton Head-area market. The available choice is not expanding uniformly, and several upper price ranges continue to generate rolling activity. The relevant alternatives around an individual property matter more than a single regional description.
For sellers, lower inventory can limit direct competition, but the slowdown in new contracts reinforces the importance of thoughtful pricing and presentation. A home should enter the market with a clear position against current alternatives and a timeline grounded in its own property type and location.
Looking Ahead
The next reports will help clarify whether September’s reduction in new listings and pending sales continues, whether improving Hilton Head-area marketing times persist, and whether the existing contract pipeline supports completed sales. In Beaufort-Jasper, the relationship between firmer pricing, longer marketing times and weaker new contracts will also be worth watching.
The Lowcountry remains a collection of distinct markets. Understanding how supply, demand and timing interact within the relevant community is the most useful starting point for a considered move.
Data Sources & Methodology
Sources: REsides, Inc. / Hilton Head Area Association of REALTORS and Lowcountry Regional MLS / Beaufort-Jasper County REALTORS; reports provided through South Carolina REALTORS, produced by ShowingTime Plus.
YoY means September 2026 versus September 2025 unless otherwise stated. MoM = (September / August - 1) x 100, rounded to one decimal using conventional half-up rounding. August regional values come from the September historical tables, which may revise figures in an earlier August publication. YTD covers January-September. Rolling comparisons are October 2025-September 2026 versus October 2024-September 2025. Monthly values are not seasonally adjusted. MLS territories are kept separate and may overlap. The HH General reports describe a narrower labeled segment and are not substituted for Hilton Head Totals. REsides dashboard figures supplied for social graphics use their own geography and filters; they are not interchangeable with these local or regional reports. Prices exclude concessions and are not same-property appreciation measures. Days on market measures listing to accepted offer. Months supply relates month-end active listings to trailing average monthly pending sales.
See More Articles